Portuguese investment funds span public and private markets, equity and credit, and a range of economic sectors. A clear comparison separates the structure of the fund from what it invests in and the conditions offered to investors.
Portugal Funds provides independent information across these strategies. We receive no commissions from funds and have no commercial incentive to favour one over another. This guide explains the main dimensions of research; it does not recommend a fund or determine personal suitability.
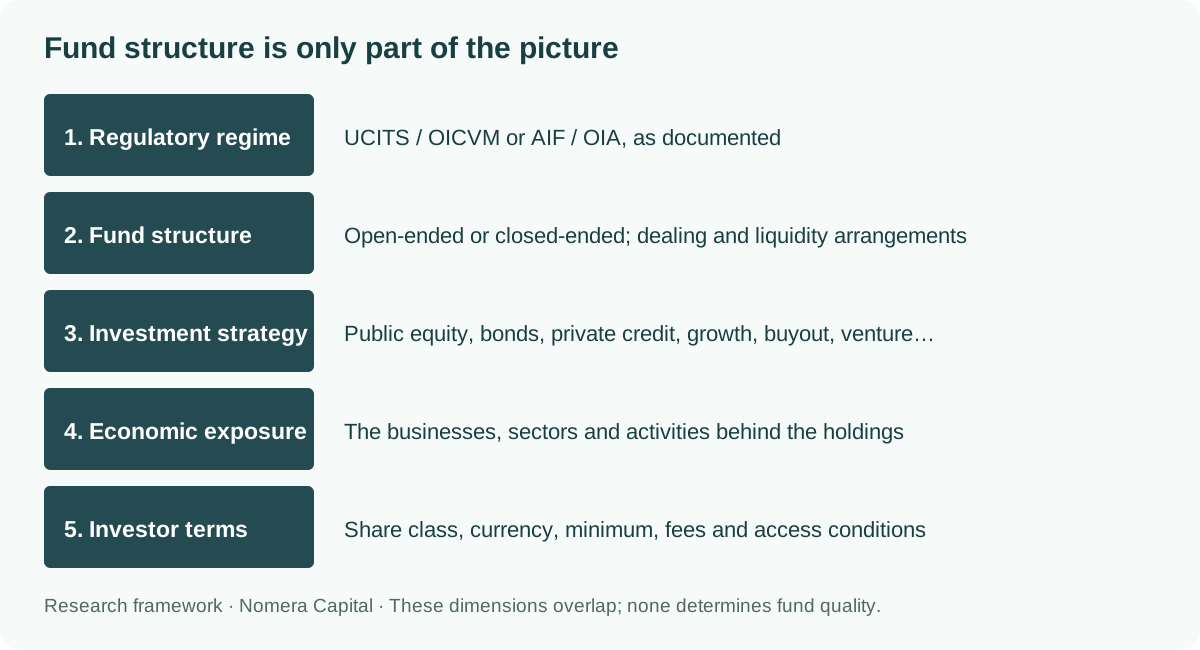
Five dimensions to keep separate
| Dimension | What to identify |
|---|---|
| Regulatory regime | The legal framework applicable to the fund and manager. |
| Fund structure | Open-ended or closed-ended, including compartments where applicable. |
| Strategy and instruments | Public equity, bonds, private equity, venture capital, private credit or mixed strategies. |
| Economic exposure | The companies, sectors, activities and assets behind the holdings. |
| Investor terms | Share class, currency, minimum, fees, access and liquidity conditions. |
These dimensions overlap but are not interchangeable. AIF is not a synonym for private equity, and open-ended is not a synonym for an equity-only strategy.
The company capital stack: debt, hybrid instruments and equity
A fund invests in an instrument as well as a business. The same company may be financed by senior lenders, subordinated lenders and equity owners, each with different contractual rights and sources of return. Repayment priority helps explain how these instruments relate.
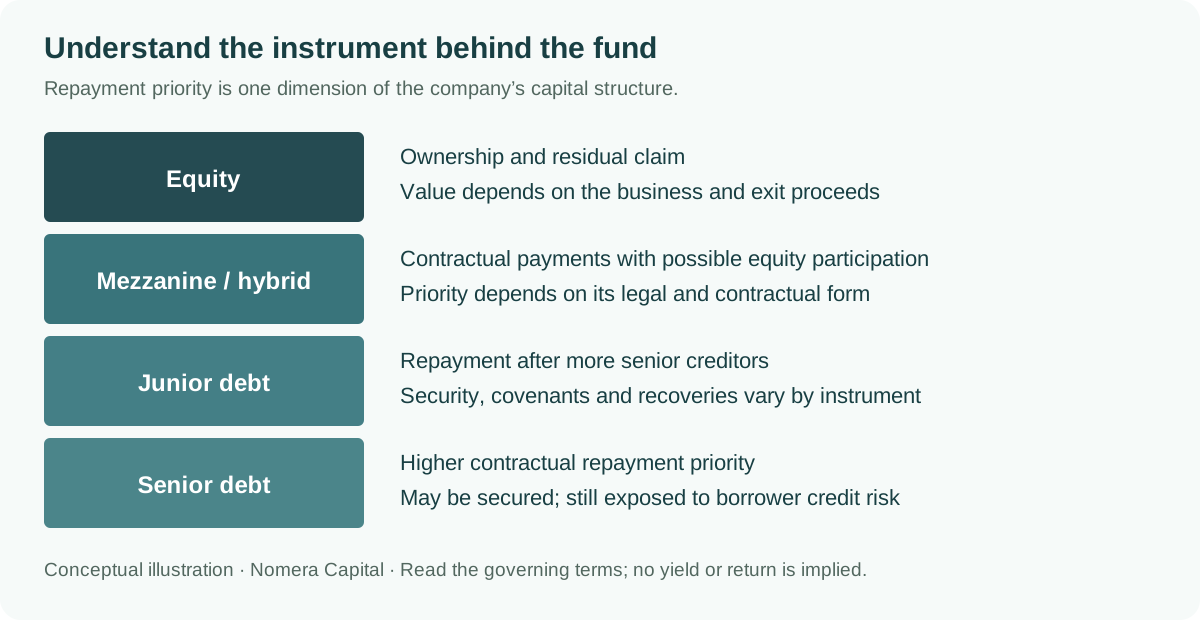
Debt returns depend on the agreed payments and the borrower's ability to meet them. Equity participates in the business's residual value and distributions. Hybrid instruments can combine these features. Check the security, covenants, voting rights and repayment arrangements rather than inferring the result from the instrument name.
Regulatory regimes and documents
Portugal’s Regime da Gestão de Ativos (RGA), introduced by Decree-Law 27/2023, distinguishes UCITS (OICVM) from Alternative Investment Funds (OIA). Regulatory category, contractual or corporate legal form, and investment strategy are separate fields. Identify each from the fund documents instead of inferring it from the marketing name or investment theme.
Read the relevant management regulations, prospectus or other governing documents, together with the class-specific terms and KID where applicable. Documents have different purposes: a presentation summarises a strategy, while the governing terms set out how the fund operates.
The KID guide explains the standardised information about product characteristics, risks, scenarios and costs.
Open-ended and closed-ended structures
| Characteristic | Open-ended | Closed-ended |
|---|---|---|
| Subscriptions | Under the fund's ongoing dealing arrangements. | During fundraising periods or other documented arrangements. |
| Investor liquidity | Redemptions under dealing, notice and settlement terms. | Distributions, maturity or permitted transfers under the documents. |
| Portfolio management | Takes account of subscriptions, redemptions and the mandate. | Takes account of investment periods, asset realisations and the mandate. |
| Terms to compare | Dealing frequency, fees, restrictions and valuation. | Term, extensions, distribution policy and transfer conditions. |
Neither structure determines investment quality. Under the RGA, funds can have a definite or indefinite duration; check the actual terms rather than assuming every closed-ended fund has a fixed maturity. A stated term is not a guarantee of an exit on a particular date. An open-ended fund's dealing terms are separate from the investor's obligations under an immigration programme.
Strategies and instruments
Public equity
Funds hold shares in listed companies. Research covers company and sector exposure, geography, allocation, dividends, trading and portfolio decisions. Use the actual portfolio to assess concentration and overlap rather than the number of constituents in a market index.
Bonds and private credit
Credit strategies hold debt claims through traded securities or privately negotiated financing. Compare the borrower, seniority, collateral, interest terms, maturity and repayment arrangements.
A contractual coupon is a payment obligation, not a guarantee that it will be paid. A loan held to maturity still has economic exposure to credit, interest rates and liquidity even without daily market quotations.
Private equity: different models of ownership
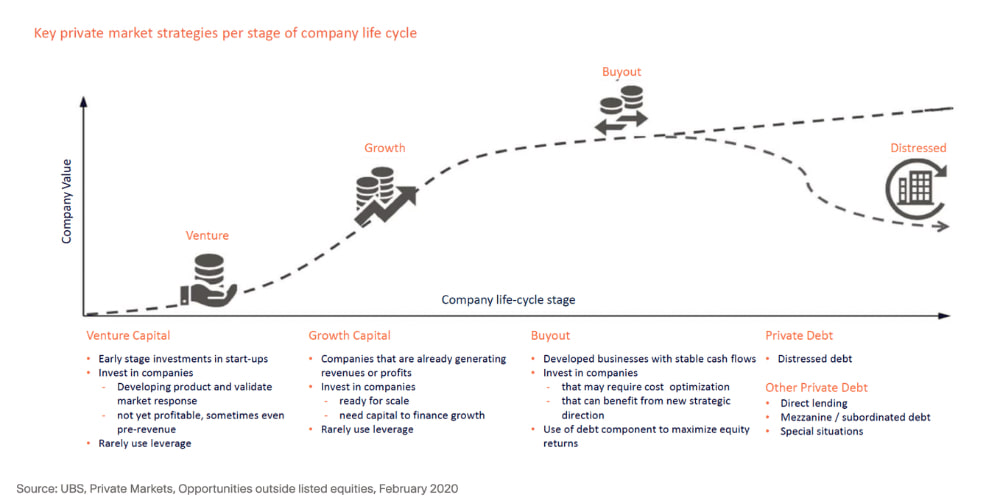
Private equity brings capital and ownership expertise to businesses outside the listed market, and sometimes to listed companies taken private. The investment case depends on the company, the price paid, the manager's ownership rights and the work planned during the holding period. Growth, buyout and turnaround funds can create value in different ways.
Growth capital: financing the next stage
Growth funds back businesses developing an established product, customer base or operating model. Capital can finance international expansion, new production capacity, product development, distribution or acquisitions. The investor may take a minority stake and work alongside the founders rather than replace them.
The research question is how additional capital translates into a stronger business. Look at the route to profitable growth, management capability, unit economics, working-capital needs and the rights agreed with existing shareholders. Growth investment does not require every company to be profitable at entry, and the use of debt varies by transaction.
Buyouts: active ownership and business development
Buyout funds acquire control of a business, often combining equity with acquisition financing. Control can give the manager scope to strengthen governance, recruit management, improve operations, expand into new markets or combine complementary businesses through a buy-and-build strategy.
Succession and shareholder transitions are examples of situations where a fund can provide both capital and continuity. For research purposes, distinguish the manager's operational plan from the financing structure: ownership control makes action possible, while the quality of execution determines the result. There is no single leverage percentage that describes all Portuguese buyouts.
Turnaround and special situations: rebuilding a business
Turnaround equity focuses on businesses that need operational or financial change. The plan may involve restoring margins, renewing management, repairing the balance sheet or repositioning a product. Distressed credit, by contrast, starts with a debt claim, although a restructuring can change the eventual ownership.
Review the resources, timescale and stakeholder agreements needed to implement the plan. The distinction is the starting instrument and the work required, rather than a label that makes one strategy universally more attractive.
| Research dimension | Growth capital | Buyout | Turnaround / special situations |
|---|---|---|---|
| Business situation | Expansion or scaling | Established business and ownership transition | Operational or financial change |
| Ownership | Often minority; rights are important | Usually control or a controlling group | Control or significant influence can be important |
| Value-creation plan | Products, capacity, distribution and market expansion | Operations, management, acquisitions and financing | Business recovery and balance-sheet restructuring |
| Financing | Transaction-specific | Equity and potentially acquisition debt | Depends on recovery and financing needs |
| Evidence to examine | Commercial progress and economics of growth | Cash generation and delivery of the ownership plan | Milestones, liquidity and implementation progress |
How private equity creates value
A practical starting point is equity value = enterprise value − net debt, with adjustments where relevant. When enterprise value is expressed as an EBITDA multiple, the interaction between operating performance, valuation and financing becomes visible.
- Operating improvement and EBITDA growth. Higher sales, stronger margins or better productivity can increase the earnings base. Research should distinguish recurring improvements from one-off adjustments.
- Cash generation and deleveraging. Cash generated by the business can reduce acquisition debt, increasing the share of enterprise value attributable to equity when other factors are unchanged. The cash is earned over the holding period; debt repayment is not free value creation.
- A change in the valuation multiple. Business quality, scale, strategic positioning and market conditions can influence what a buyer is willing to pay. Multiple expansion can contribute to a return, but an investment case can also be assessed with an unchanged or lower exit multiple.
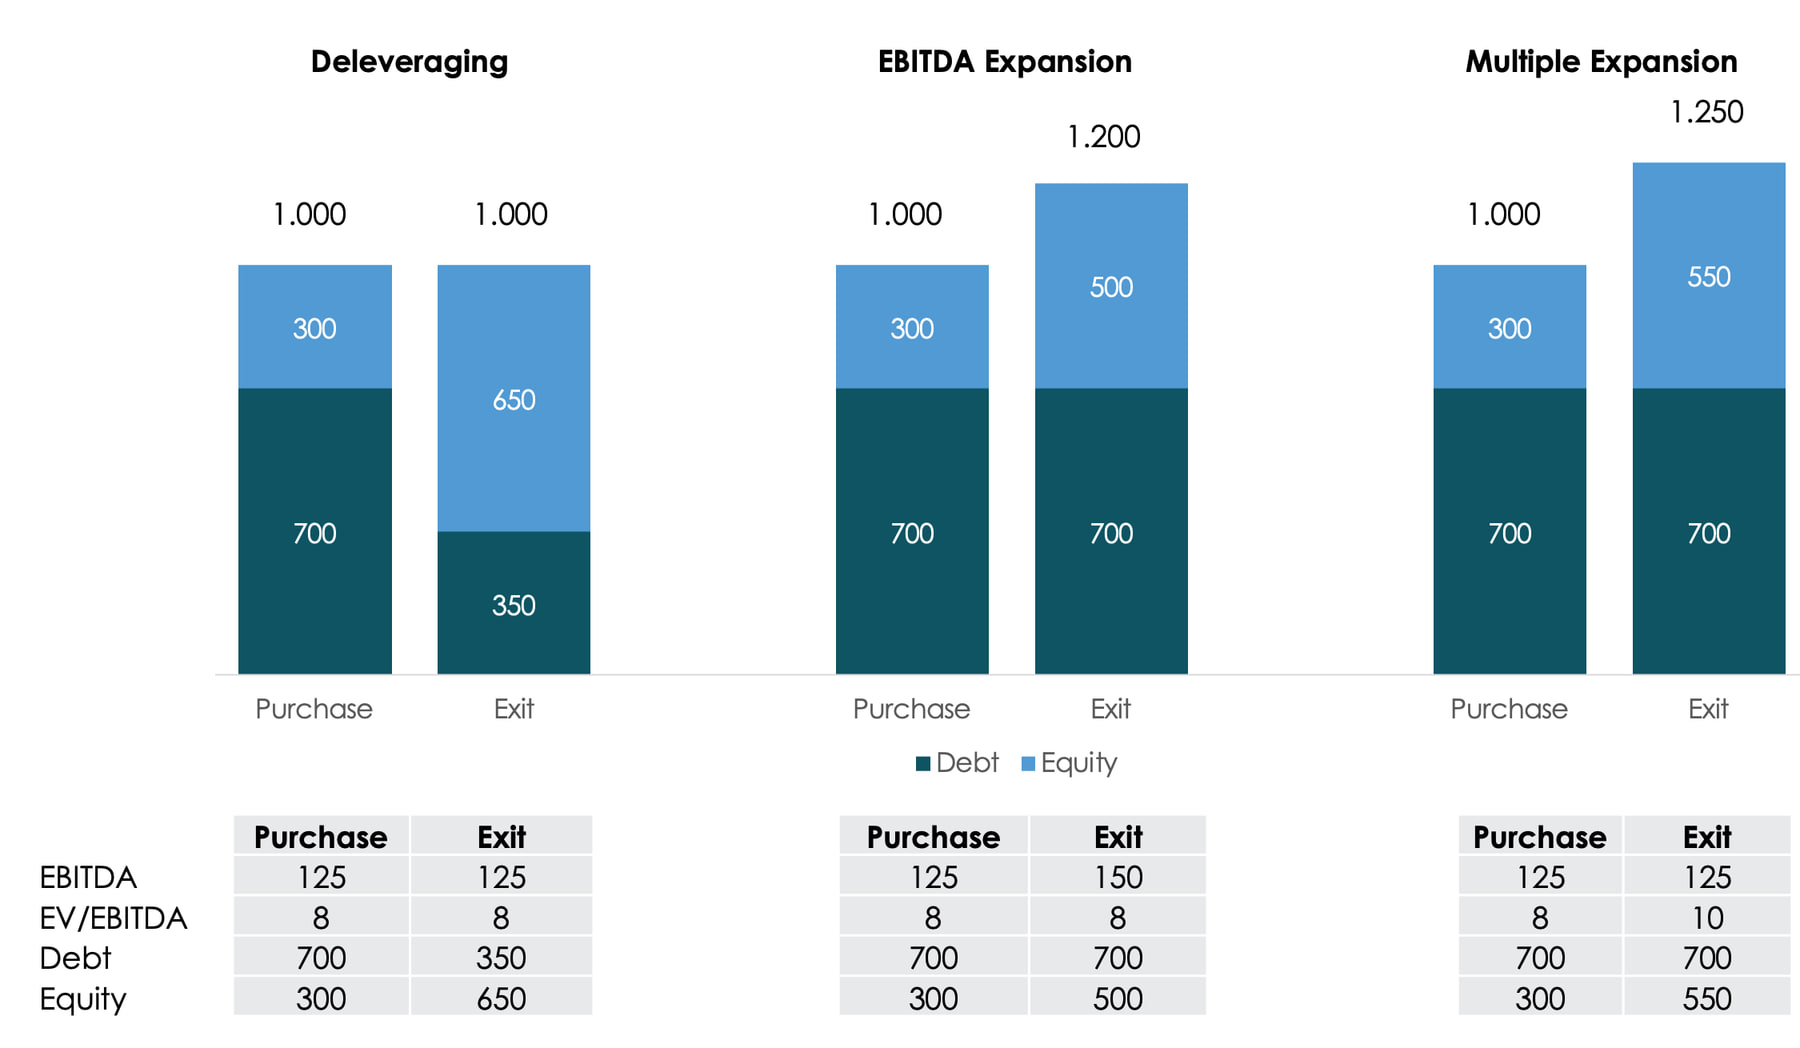
The illustration isolates each lever. With enterprise value unchanged at 1,000, reducing debt to 350 leaves equity of 650. Raising EBITDA from 125 to 150 at an unchanged 8× multiple gives enterprise value of 1,200 and equity of 500 with debt held at 700. Raising the multiple from 8× to 10× at unchanged EBITDA gives enterprise value of 1,250 and equity of 550.
These are company-level equity values before fund fees, carried interest, taxes and other investor-level effects. They contain no holding-period assumption and therefore do not state an annualised investor return. In a real investment, operating performance, debt and valuation can change together.
Venture capital: supporting companies through development
Venture funds finance businesses at different stages, from product development to international expansion. The manager can contribute recruitment, governance, commercial introductions and access to later funding rounds as well as capital.
| Stage | What the capital can support | What to research |
|---|---|---|
| Seed | Product development, customer testing and the first team | Evidence of demand, execution and funding runway |
| Series A / early growth | Building a repeatable commercial model | Customer retention, unit economics and the cost of scaling |
| Later-stage venture | Expansion, acquisitions and preparation for an exit | Growth quality, valuation, financing needs and exit routes |
Returns can be concentrated in a small number of successful companies. Examine portfolio construction, follow-on reserves, dilution and the manager's contribution across both successful and unsuccessful investments. Funding-round names do not establish a standard investment size, risk level or promised return.
Private credit: financing the business through debt
Private credit can include senior direct lending, junior debt, mezzanine and special situations. The underlying instrument determines repayment priority, security, interest, covenants and possible participation in equity upside.
| Instrument | Main economic characteristics | Documents and evidence to compare |
|---|---|---|
| Senior direct lending | Contractual interest and higher repayment priority | Security, covenants, borrower cash flows and repayment source |
| Junior / subordinated debt | Ranks behind more senior creditors | Intercreditor terms, leverage and recovery assumptions |
| Mezzanine / hybrid | Debt payments with possible warrants or conversion rights | Cash versus capitalised interest, dilution and participation terms |
| Distressed / special situations | Debt linked to a restructuring or recovery plan | Legal priority, restructuring milestones and recovery economics |
A contractual coupon is a payment obligation, not a guarantee. Holding a private loan without daily quotations changes how its value is observed; it does not remove credit, interest-rate or liquidity exposure. Compare the actual loan and fund terms rather than assuming a standard maturity or return range.
Historical references: fundraising and performance
The charts below provide historical industry context. Their dates and populations matter: they are industry references, not current offers, forecasts or a proxy for the returns of Portuguese Golden Visa funds.
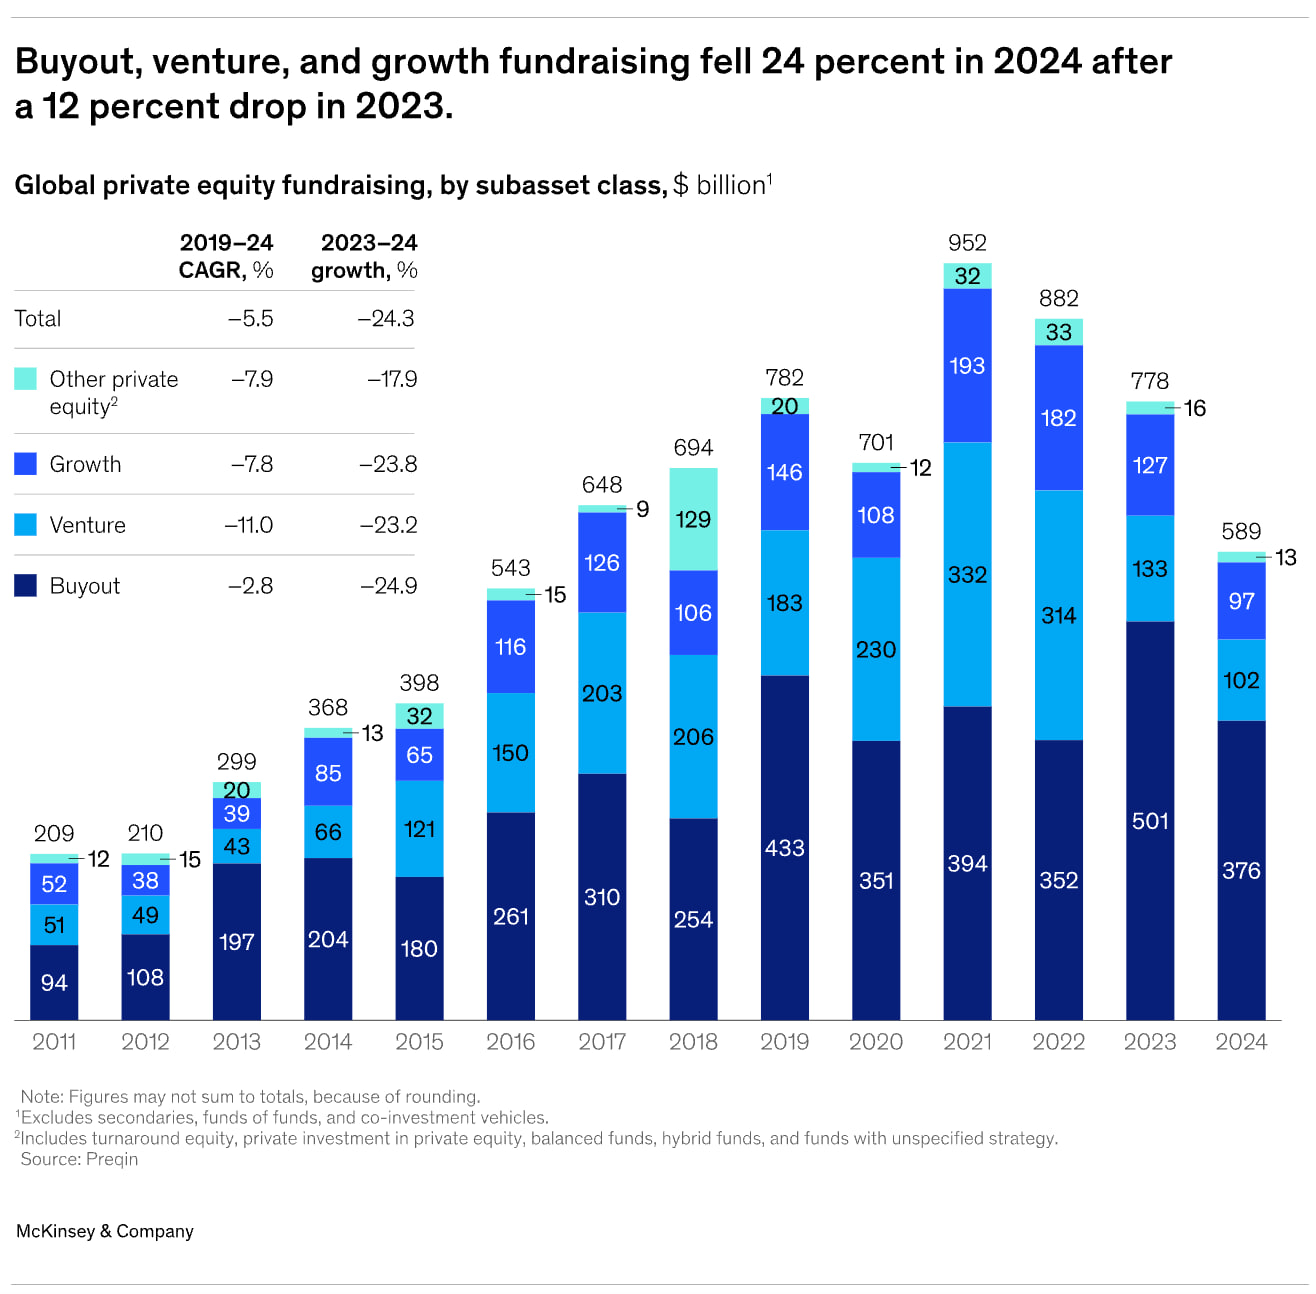
The fundraising exhibits separate buyout, growth, venture and other strategies. Their different periods, regions and currencies prevent a direct comparison of the headline totals. The original global source is McKinsey's 2025 report.
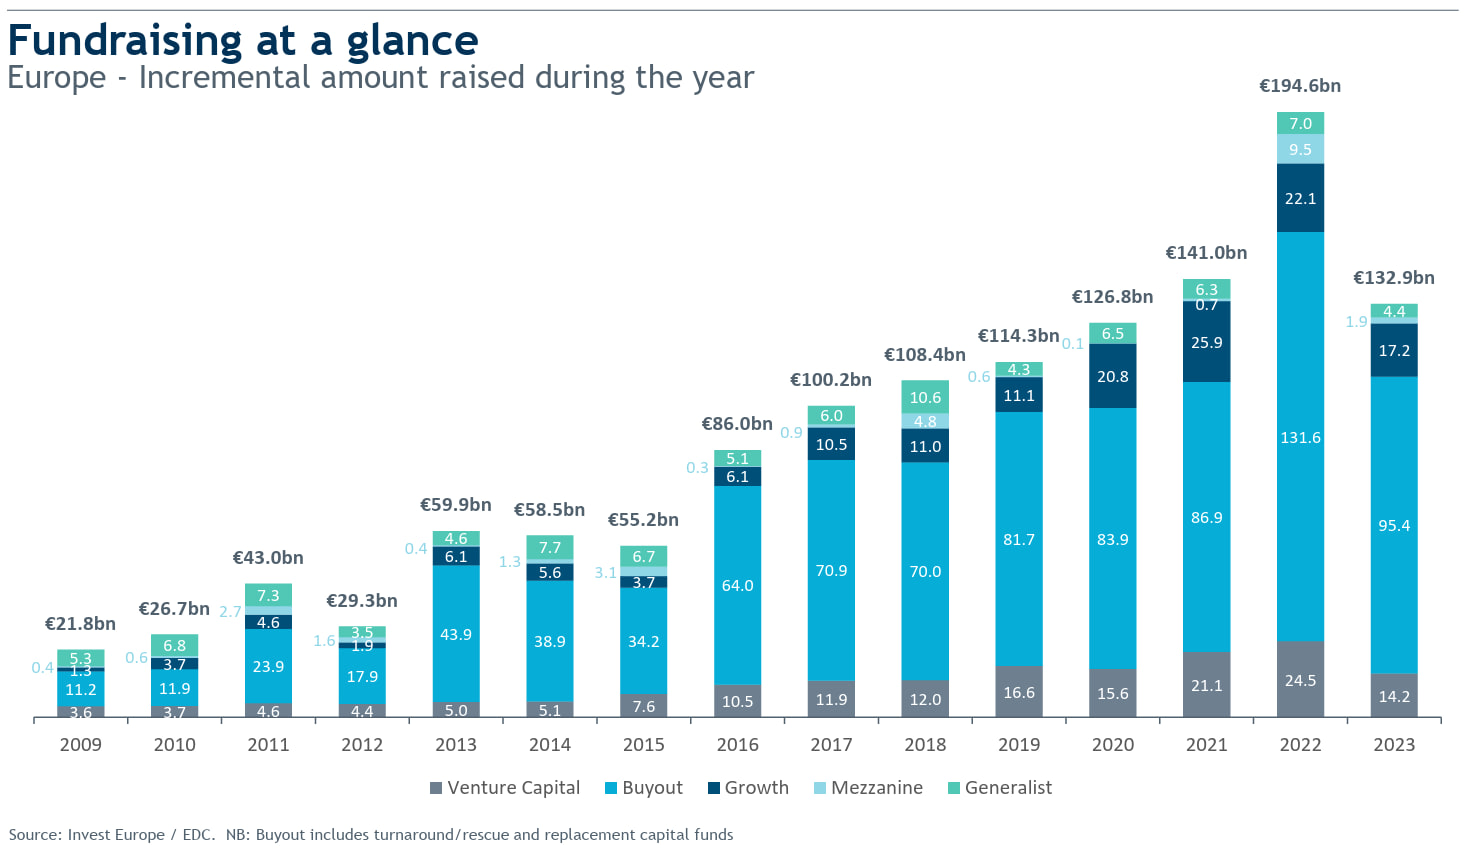
Invest Europe's 2023 activity publication is the reference for the European chart. These are dated exhibits, not the latest fundraising totals.
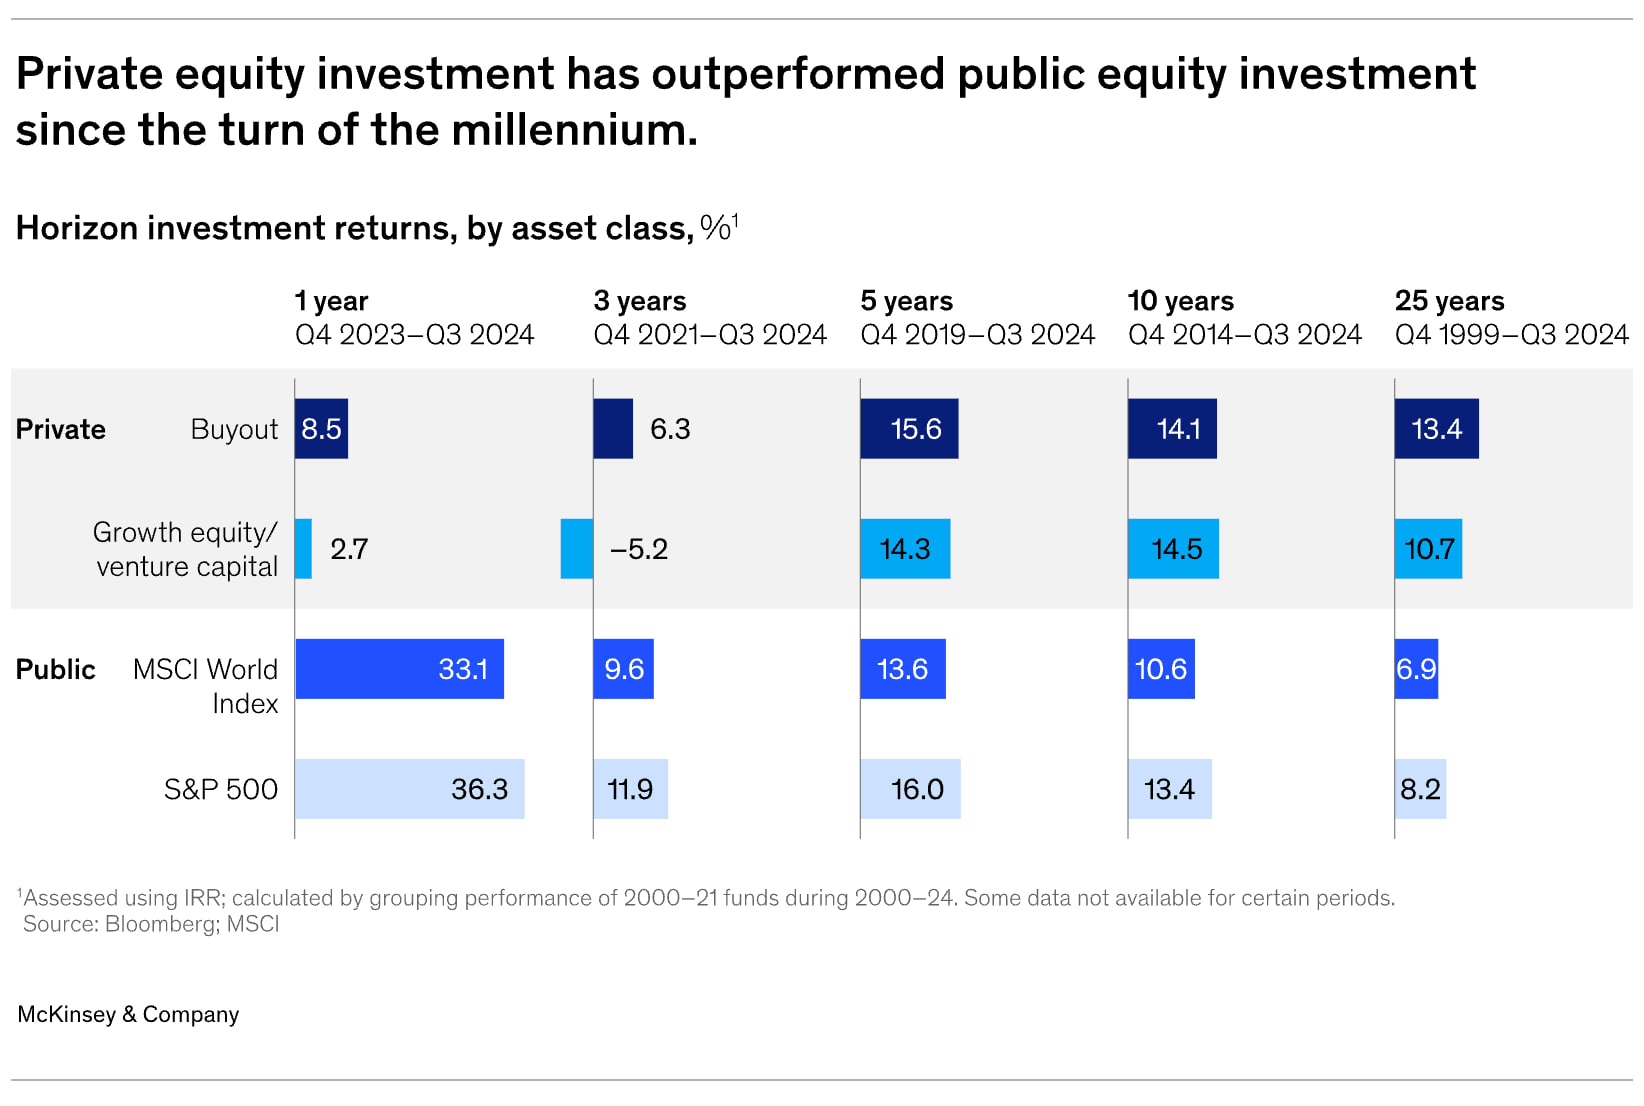
| Reference in the original exhibit | 1 year | 5 years | 10 years |
|---|---|---|---|
| Buyout | 8.5% | 15.6% | 14.1% |
| Growth equity / venture capital | 2.7% | 14.3% | 14.5% |
| MSCI World | 33.1% | 13.6% | 10.6% |
| S&P 500 | 36.3% | 16.0% | 13.4% |
Historical figures transcribed from the original exhibit; each horizon ends in Q3 2024. Refer to its methodology and populations rather than treating these as the return of a Portuguese fund.
Read the horizons together: the exhibit shows stronger one-year public-market figures and higher private-market figures over some longer periods. Its private-market observations use an IRR-based fund aggregation. They should not be treated as an investable like-for-like portfolio or transferred to an individual fund's target return.
For a fund-specific comparison, identify vintage, strategy, region, currency, cash-flow timing, realised proceeds, remaining valuations and whether the return is gross or net. IRR captures cash-flow timing; TVPI combines distributions and residual value relative to paid-in capital; DPI records distributions relative to paid-in capital. A public-market-equivalent analysis can apply the same dated cash flows to a stated index, with its own methodology. ILPA's performance-reporting framework helps distinguish fund-level and portfolio-level results and gross versus net reporting.
A useful selection question across public and private markets is the same: what has the manager delivered, through which investment decisions, and how much reaches the investor after costs?
Follow the underlying exposure
An investment in shares or a loan can link the fund to an operating business, a holding company or another vehicle. Hospitality, collectibles and digital assets should be described alongside other exposures through the same factual framework.
Record what the fund directly holds and what has been established about the economic activities beneath it. See Understanding Underlying Fund Exposures.
Fees and investor classes
Compare subscription, management, performance and redemption fees, other expenses and their calculation bases. Conditions can vary across classes and accounts. A performance fee may depend on a hurdle, high-water mark or waterfall; the percentage alone does not explain the outcome.
A hypothetical model can show how these definitions interact. It does not predict asset performance. Our guide to fund terms and fees provides a comparison framework.
Performance and research models
Separate historical performance, manager targets, regulatory scenarios and illustrations. For private markets, distinguish realised distributions from estimated remaining value; read IRR alongside TVPI and DPI.
Our proprietary Stock Picking Ability and Downside Protection models analyse historical portfolio decisions for funds with published assessments. They are distinct from a manager company's financial data or score. Read each result with its date and methodology.
Golden Visa: a separate legal assessment
AIMA's fund-route requirements describe a minimum investment of EUR 500,000 in Portuguese non-real-estate collective investment undertakings, with at least five years' maturity at the time of investment and at least 60% of investments in companies headquartered in Portugal.
The fund-maturity condition is separate from the investor’s minimum maintenance period. Article 65-B of Regulatory Decree 84/2007 counts that minimum five-year period from the grant of the residence permit, rather than the subscription date. AIMA’s current FAQs also distinguish maintaining an investment for ARI renewals from the conditions applying after an autonomous permanent residence permit has actually been granted. Five years passing does not itself authorise a redemption or guarantee fund liquidity.
Confirm the proposed subscription and supporting documents with qualified immigration counsel. Regulatory registration, database classification, availability for subscription and legal eligibility are distinct. The relevant dates and treatment of distributions should be checked for the specific investment and application.
Investor access
Review the relevant class and provider conditions for US persons, Self-Directed IRA arrangements, jumbo accounts and other access requirements. Record Shariah status and any supporting certification separately.
Self-service research and optional support
Subscribe to Portugal Funds for self-service access to research, source documents and analytical tools. A consultation is not required to explore the subscription.
Our optional research consultancy supports understanding documentation, exposures, fee mechanics and analytical findings. We are not authorised to provide investment advice and do not make personal fund recommendations or assess suitability.
Fund providers can contact the Portugal Funds team to review the information we hold about their organisation and funds and supply factual corrections or updated documents.